Term Life and Whole Life Insurance Explained
Term life and whole life are two common forms of life insurance, but they are designed differently. Both can provide a death benefit to eligible beneficiaries when the insured person dies while applicable coverage is in force, yet their duration, premium structure and additional features can differ significantly.
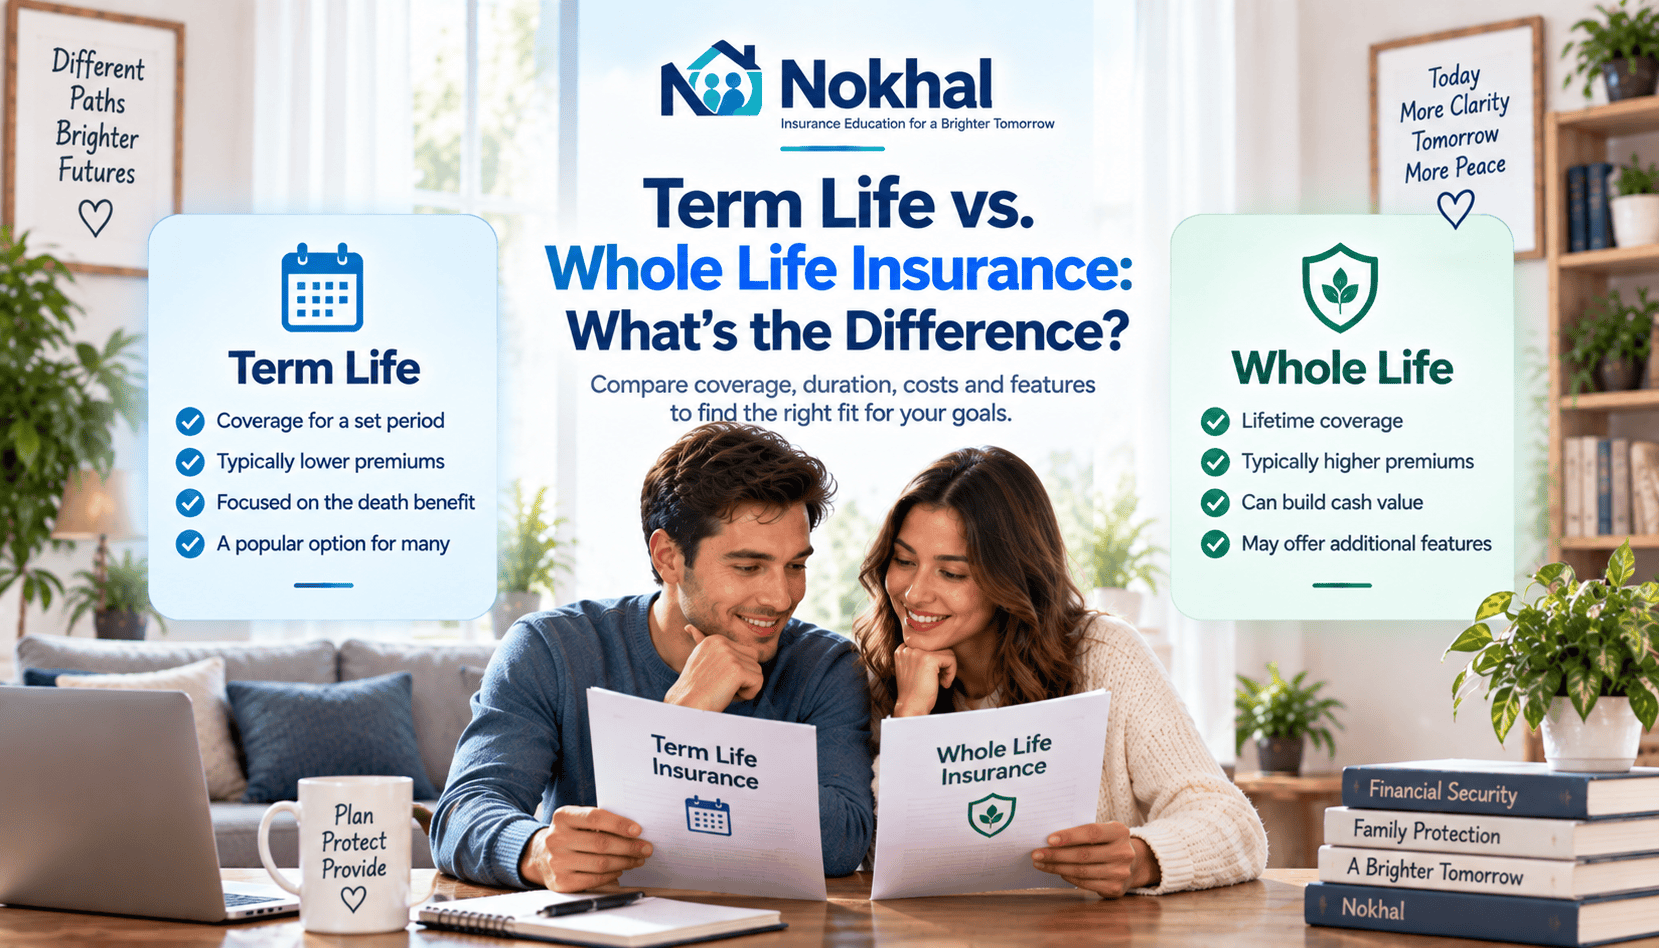
Term life insurance generally provides coverage for a specified period. Whole life insurance, by contrast, is a form of permanent life insurance designed to provide coverage for life when the policy’s requirements are satisfied. Whole life policies also typically include a cash value component.
Understanding these structural differences is more useful than simply asking which type is “better.” Each policy must be evaluated according to its own terms, costs, guarantees, exclusions and features.
What Is the Main Difference?
The simplest distinction is duration and policy structure. Term insurance focuses primarily on providing life insurance protection during a defined term. Whole life combines permanent death-benefit protection with a cash value feature.
Coverage for a defined period
Designed to provide protection for a specified term, subject to the contract.
Temporary coverage structurePermanent life insurance
Designed for long-term coverage and typically includes a cash value component.
Permanent coverage structureHow Does Term Life Insurance Work?
A term life policy generally provides coverage for a specified number of years or another defined period stated in the contract. If the insured person dies while applicable coverage is in force, an eligible death benefit can be paid to the designated beneficiaries.
What happens at the end of a term depends on the policy. Some policies may offer renewal or conversion provisions, while others may operate differently. Any continuation of coverage can involve different premiums or conditions.
How Does Whole Life Insurance Work?
Whole life insurance is a type of permanent life insurance. Rather than being designed around a limited term, it is generally intended to remain in force for the insured person’s lifetime as long as the policy requirements are satisfied.
A traditional whole life policy typically combines a death benefit with a cash value component. The guarantees and mechanics of the policy depend on the contract and insurer.
Provides eligible protection for beneficiaries.
Designed for long-term rather than fixed-term coverage.
Typically includes a value component within the policy.
Term Life vs. Whole Life: Side-by-Side
Looking at the main characteristics together makes the structural differences easier to understand.
This comparison describes general characteristics. Actual premiums, guarantees and policy features vary by insurer and contract.
Why Can the Premiums Be Different?
Term life insurance often has a lower initial premium than whole life insurance for a comparable death benefit because the coverage is designed for a limited period and generally does not include a cash value component.
Whole life insurance typically has a different cost structure because it is designed as permanent insurance and includes additional policy features. This does not mean that one policy will always cost a specific amount relative to another. Pricing depends on the insurer, coverage amount, underwriting and contract.
Primarily focused on death-benefit protection.
Permanent structure plus a cash value component.
What Does Cash Value Mean?
Cash value is a feature associated with certain permanent life insurance policies, including whole life. A portion of the policy’s structure contributes to a value that can develop over time according to the contract.
Policy owners may have ways to access available cash value, such as through certain withdrawals or policy loans, depending on the contract. Accessing those values is not the same as receiving free money from the insurer.
Loans, withdrawals or other uses of policy values can affect cash value, the death benefit or other policy features. The effect depends on the specific contract.
Both Types Can Provide a Death Benefit
Despite their differences, both term and whole life insurance share an important purpose: they can provide a death benefit to eligible beneficiaries after the insured person’s death when the applicable policy requirements have been satisfied.
The amount payable can be affected by the policy’s terms and any circumstances that alter the benefit. The actual insurance contract controls how a claim is evaluated.
What Happens When a Term Life Policy Ends?
Reaching the end of the original term is one of the key differences between term and whole life insurance. A term policy is not automatically identical to permanent insurance simply because the insured person has reached the end of the initial coverage period.
Depending on the contract, options might include expiration, renewal or conversion to another form of coverage. Renewal premiums can differ substantially from those charged during the original term, and conversion provisions can have their own deadlines and conditions.
Questions That Help Explain the Difference
Instead of viewing term and whole life as interchangeable products, it can be useful to understand the questions each policy answers.
How long is the coverage designed to remain in force?
Does the policy contain a cash value component?
How are premiums structured under the contract?
What happens when the initial coverage period ends?
What guarantees and conditions are stated in the policy?
How could changes to the policy affect its benefits?
The Biggest Difference Is How the Policies Are Structured
Term life insurance generally provides death-benefit protection for a specified period and usually does not build cash value. Whole life insurance is a form of permanent coverage that typically combines a death benefit with a cash value component. Premiums, guarantees, duration and other features depend on the individual policy and insurer.