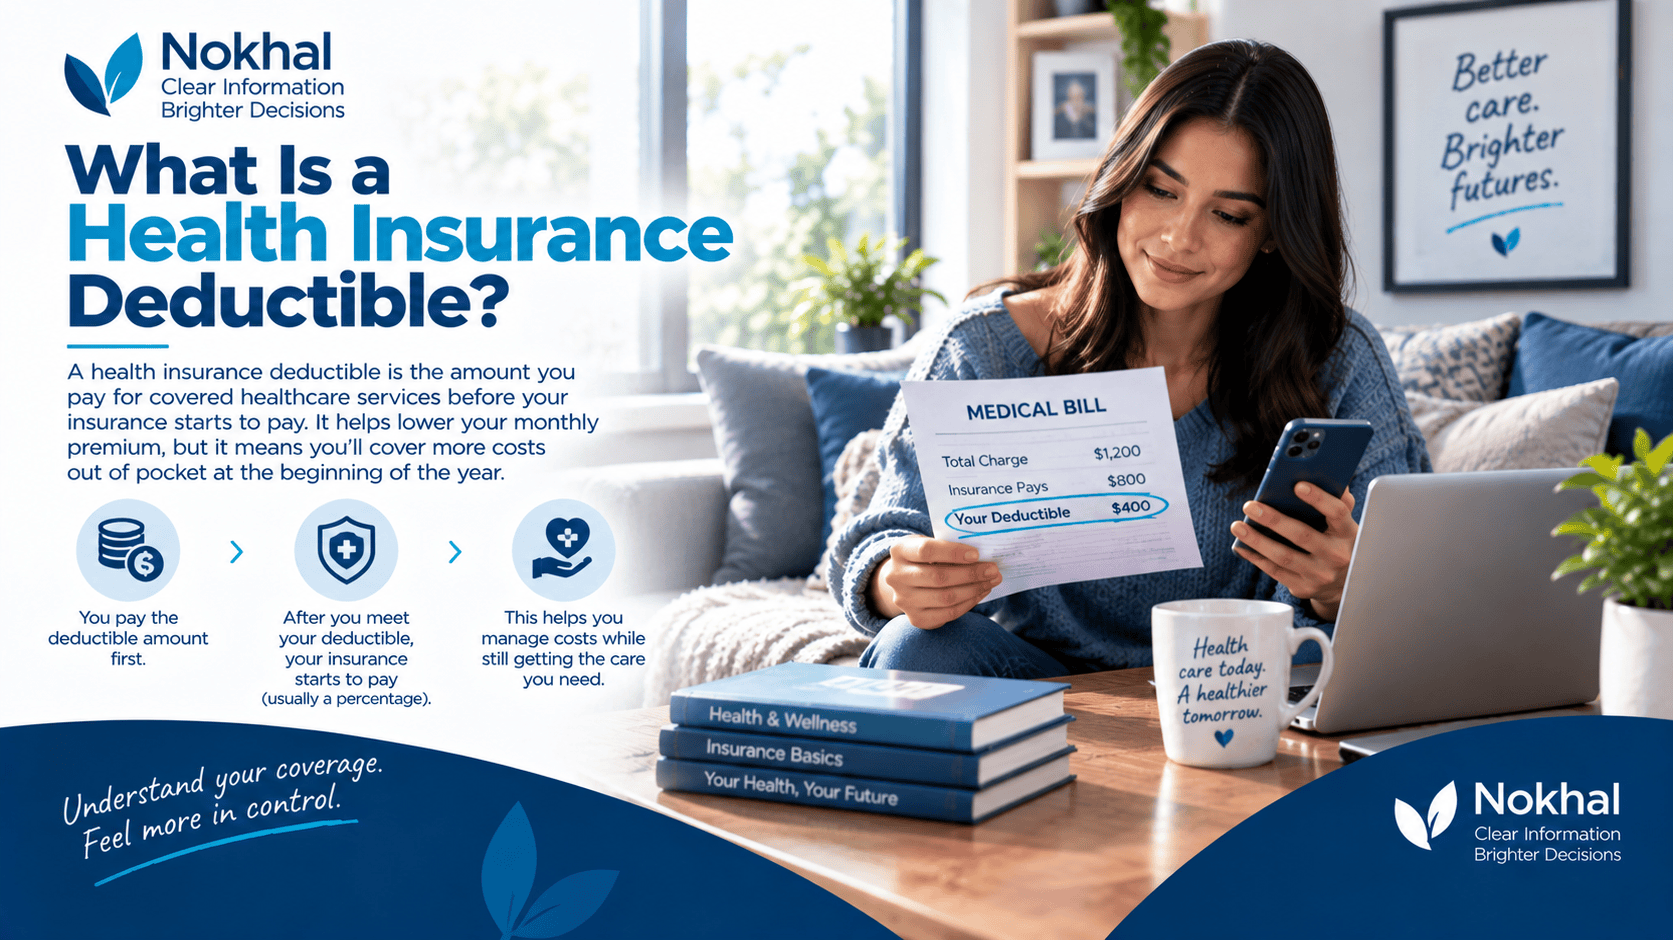
A health insurance deductible is the amount you generally pay for certain covered health care services before your insurance plan begins paying its share. Understanding your deductible can help you estimate your medical costs throughout the year.
What Is a Health Insurance Deductible?
A deductible is the amount you pay for certain covered health care services before your health insurance plan begins paying its share. For example, if your plan has a $2,000 deductible, you generally pay the first $2,000 of covered services that are subject to the deductible.
The deductible is one part of health insurance cost-sharing. Other costs can include your monthly premium, copayments and coinsurance.
Not every service necessarily requires you to meet the deductible first. Many health plans cover certain preventive services before the deductible is reached, and the exact rules depend on the plan.
How Does a Deductible Work?
Suppose you have a health insurance plan with a $1,500 deductible. During the year, you receive covered medical services that are subject to the deductible.
Until you have paid $1,500 toward those services, you may generally be responsible for the allowed cost of the care. Once you reach the deductible, your plan begins sharing costs according to its copayment or coinsurance rules.
For example, after reaching a $1,500 deductible, your plan might require you to pay 20% coinsurance for a covered service while the insurance company pays the remaining 80%, subject to the plan’s terms.
Deductible vs. Copay and Coinsurance
A deductible is different from a copay and coinsurance. The deductible is the amount you generally pay before your plan starts sharing costs for certain covered services.
A copay is usually a fixed dollar amount that you pay for a covered service, such as $30 for a doctor’s visit. A coinsurance payment is generally a percentage of the allowed cost, such as 20% of a covered service.
For example, imagine a plan with a $1,000 deductible, a $30 copay for primary care visits and 20% coinsurance after the deductible. The plan’s rules determine which services are subject to the deductible and when the copay or coinsurance applies.
These three types of cost-sharing can work together, so understanding each one is important when estimating the total cost of a health insurance plan.
Your Deductible Is One Part of Your Total Health Care Costs
A deductible determines how much you may need to pay for certain covered services before your insurance plan begins sharing costs. To understand your potential expenses, you should also consider the monthly premium, copayments, coinsurance and out-of-pocket maximum.
What Happens After You Meet Your Deductible?
Once you have met your deductible, your health insurance plan generally begins paying its share of covered services according to the plan’s cost-sharing rules.
Depending on the plan, you may then pay a fixed copayment or a percentage through coinsurance. You may continue paying these amounts until you reach the plan’s out-of-pocket maximum.
The out-of-pocket maximum is the most you generally pay during a plan year for covered services under the applicable plan rules. Once you reach that limit, the plan generally pays 100% of covered benefits for the rest of the plan year.
Do All Health Insurance Plans Have the Same Deductible?
No. Deductibles vary from one health insurance plan to another. Some plans have low deductibles and higher monthly premiums, while others may have higher deductibles and lower monthly premiums.
Family plans can also have different deductible structures. A plan may have both an individual deductible for each person and a family deductible that applies to the household as a whole.
Some plans can also have separate deductibles for different types of services, such as prescription drugs. The specific structure should be reviewed in the plan documents before enrolling or receiving care.
What Is a High-Deductible Health Plan?
A high-deductible health plan, often called an HDHP, is a type of health plan with a higher deductible and generally lower monthly premiums than plans with lower deductibles.
Some HDHPs are eligible to be paired with a Health Savings Account, or HSA. An HSA allows eligible individuals to set aside money on a pre-tax basis for qualified medical expenses, including deductibles, copayments and coinsurance.