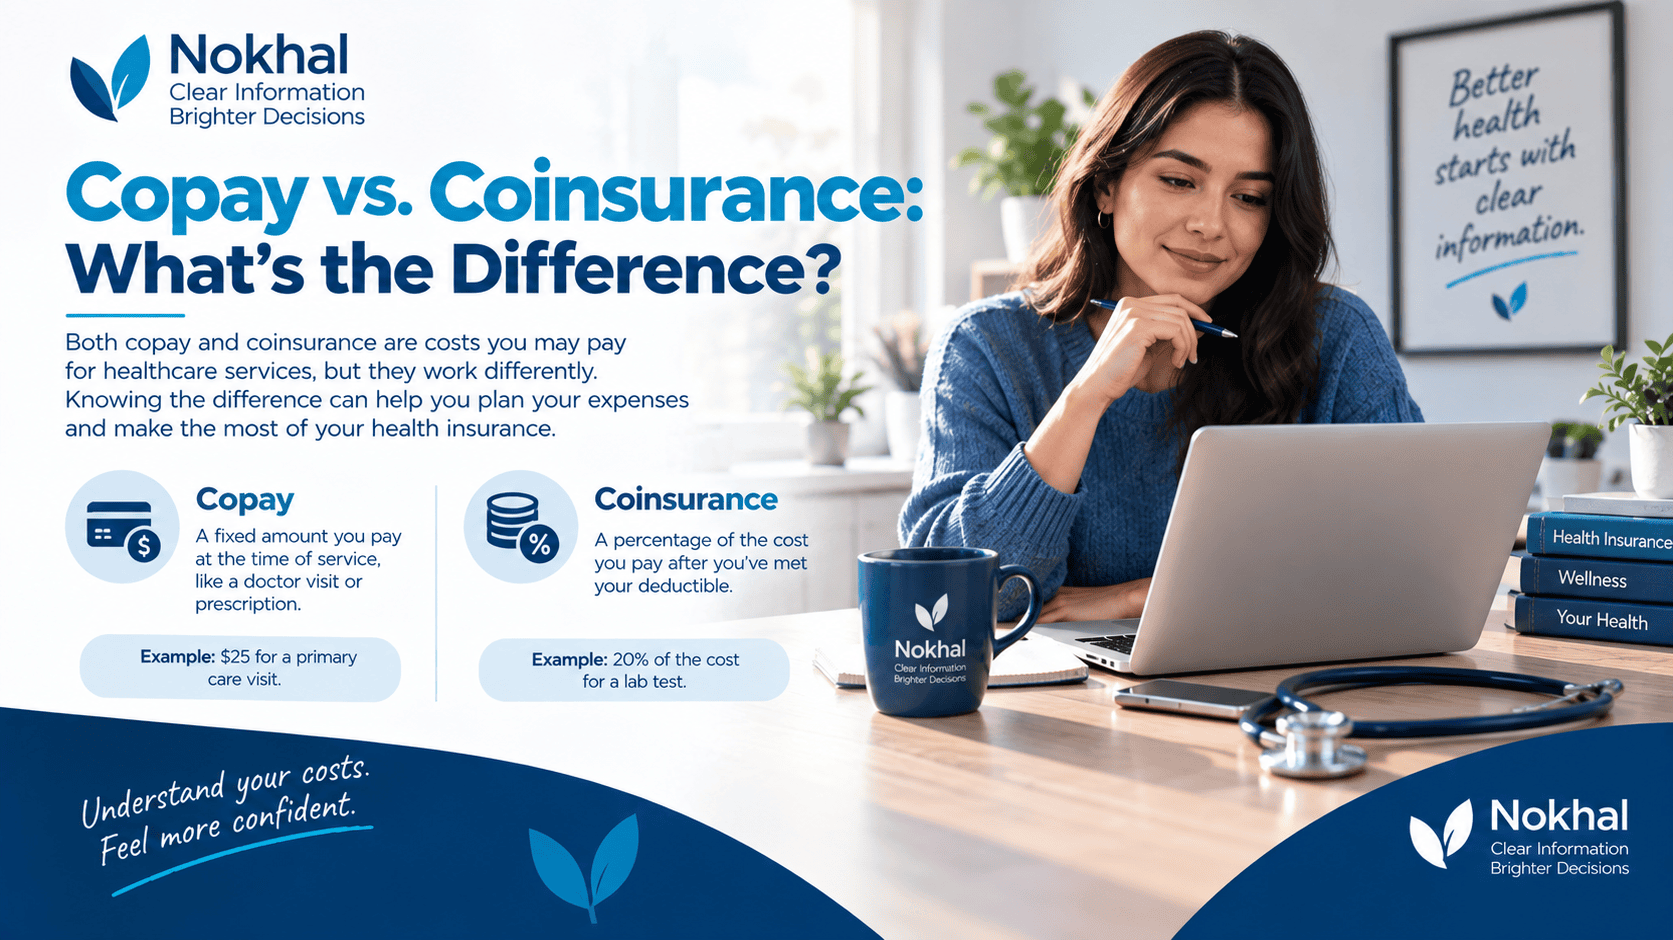
Copay and coinsurance are two common ways health insurance plans share medical costs with you. Although both require you to pay part of the cost of covered care, they work differently.
What Is a Copay?
A copay, or copayment, is a fixed amount you pay for a covered health care service. For example, your health insurance plan might require a $30 copay for a doctor’s visit.
Unlike coinsurance, a copay is generally a specific dollar amount rather than a percentage of the medical bill. The amount can vary depending on the type of service.
For example, a health plan could have one copay for a primary care visit, another for a specialist visit and a different amount for prescription drugs. The exact amounts depend on the plan.
What Is Coinsurance?
Coinsurance is the percentage of the cost of a covered health care service that you pay, usually after you have met your deductible.
For example, suppose your health insurance plan has 20% coinsurance and the allowed amount for a covered medical service is $500. If the coinsurance applies, you would pay $100 and the insurance plan would pay the remaining $400.
Because coinsurance is based on a percentage, the amount you pay can change depending on the cost of the covered service. A more expensive service can therefore result in a larger coinsurance payment.
Copay vs. Coinsurance: A Simple Example
Imagine that you need a medical service with an allowed cost of $500.
With a 20% coinsurance, you would generally pay $100 of the $500 allowed amount after meeting any applicable deductible. The insurance plan would pay the remaining $400.
With a $40 copay, you would generally pay the specified $40 copayment for that covered service, according to the plan’s rules.
This illustrates the main difference: a copay is a predetermined dollar amount, while coinsurance changes according to the cost of the covered service.
Copay Is Fixed, Coinsurance Is Percentage-Based
The simplest way to remember the difference is that a copay is usually a fixed dollar amount for a covered service, while coinsurance is a percentage of the allowed cost. Your plan may use one, the other, or both depending on the type of care you receive.
How Does the Deductible Affect Copays and Coinsurance?
The deductible is another important part of health insurance cost-sharing. It is the amount you generally pay for certain covered health services before your plan begins paying its share.
After you meet the deductible, you may pay a copay or coinsurance for covered services, depending on your plan. Some plans may cover certain services before the deductible is met.
For example, if a plan has a $1,500 deductible and 20% coinsurance, you may have to pay the applicable deductible for certain services first. After reaching the deductible, the plan may begin sharing costs according to the coinsurance rules.
How Do Copay and Coinsurance Affect Your Total Costs?
Copays and coinsurance are both considered out-of-pocket costs. When comparing health insurance plans, it is important to look beyond the monthly premium and consider the deductible, copays, coinsurance and out-of-pocket maximum.
The out-of-pocket maximum limits how much you generally pay for covered services during a plan year. Once you reach the applicable limit, the plan generally pays 100% of covered benefits for the remainder of the plan year, subject to the plan’s rules.
For 2026 Marketplace plans, the out-of-pocket maximum cannot exceed $10,600 for an individual or $21,200 for a family. Specific plans can have lower limits.