Personal property coverage helps protect the belongings inside your home when they are damaged or stolen because of a covered event. Learn what it covers, how limits work, and how claims may be paid.
What Is Personal Property Coverage?
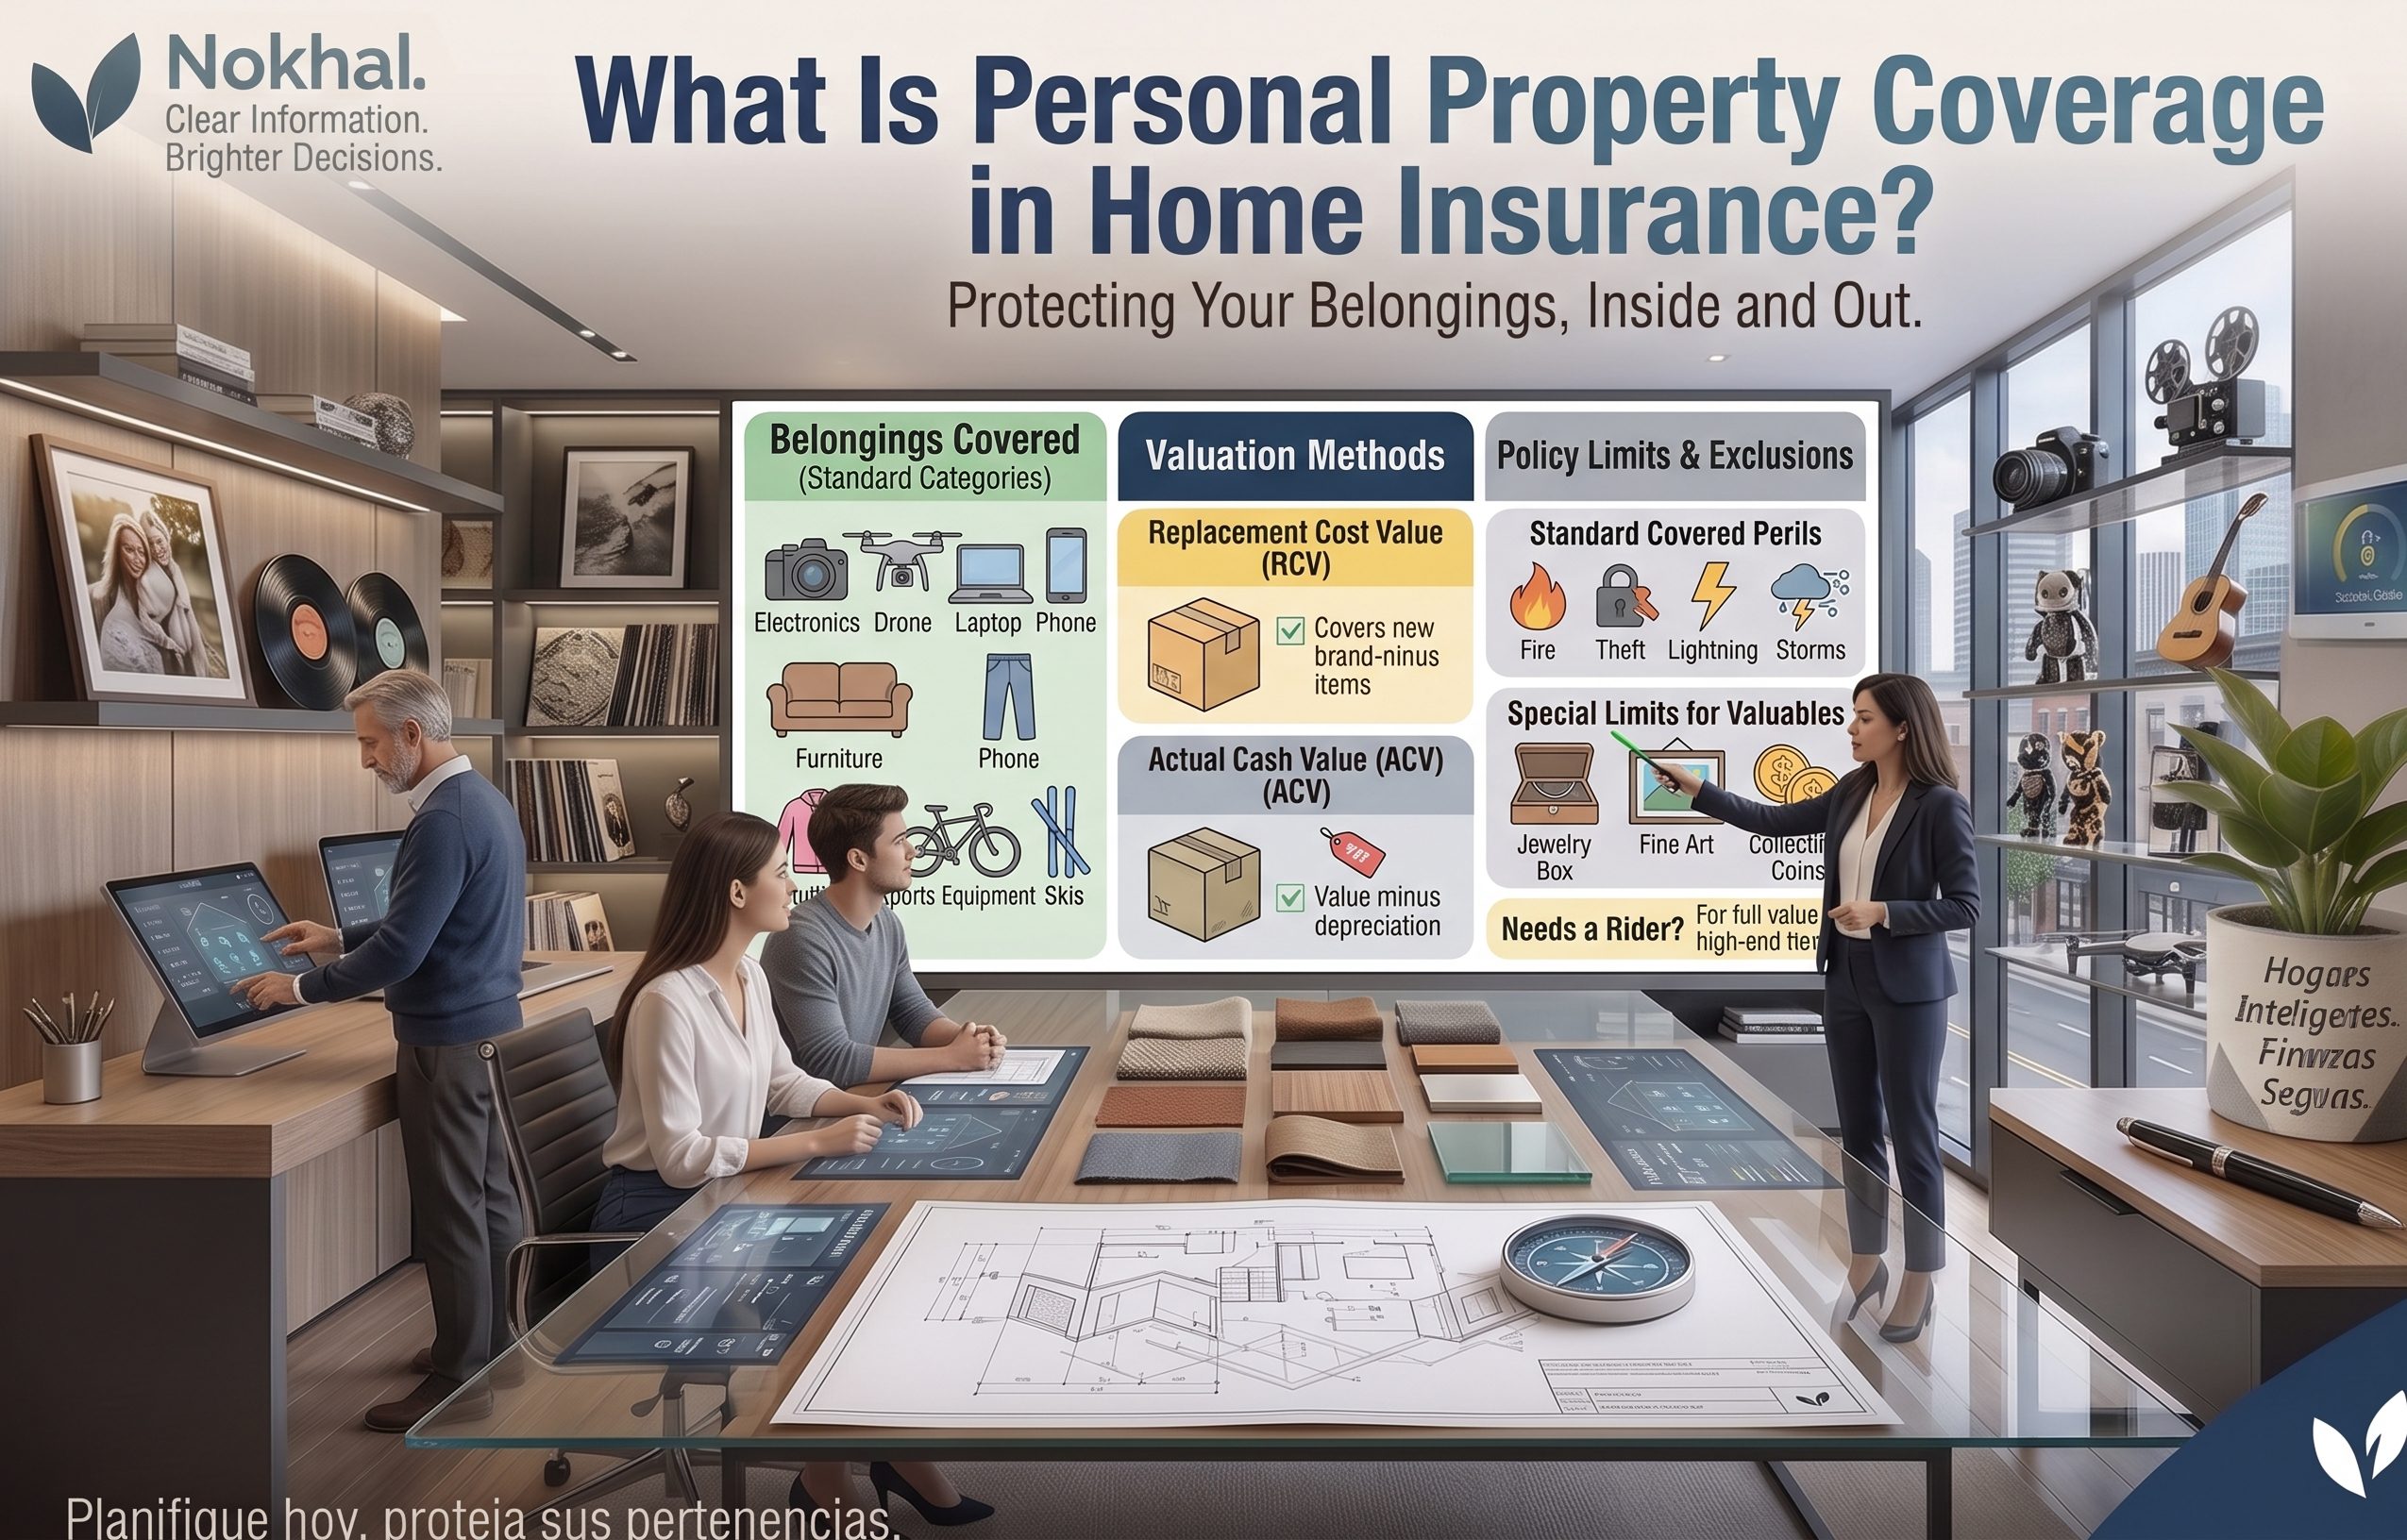
Personal property coverage is the part of a homeowners insurance policy that can help protect your belongings when they are damaged, destroyed, or stolen because of a covered event. This can include everyday items such as furniture, clothing, electronics, and sporting equipment.
The exact amount of coverage depends on the policy. Many standard homeowners policies set personal property coverage at a percentage of the amount used to insure the home’s structure, although limits and terms vary by insurer and policy.
What Does Personal Property Coverage Include?
Personal property coverage can apply to many of the belongings you use in your everyday life. Coverage generally depends on whether the cause of loss is included in your policy and whether any special limits or exclusions apply.
1. Furniture, Clothing, and Electronics
Furniture, clothing, televisions, computers, and other personal belongings may be covered when they are stolen or damaged by a covered event such as a fire or another insured disaster.
2. Belongings Away From Home
Personal property coverage may also extend to belongings while they are away from your home. For example, some policies provide protection for personal items that are stolen while you are traveling. Specific limits may apply depending on the policy.
How Are Personal Belongings Valued?
3. Actual Cash Value
With actual cash value coverage, a claim payment generally reflects the item’s replacement cost minus depreciation. This means an older item may be worth less for insurance purposes than the price of buying a new replacement.
4. Replacement Cost
Replacement cost coverage generally pays the amount needed to replace damaged personal property with an item of similar kind and quality without deducting depreciation, subject to the policy’s terms, limits, and deductible.
What About Expensive Personal Items?
Certain valuable belongings may have special dollar limits under a standard homeowners policy. Jewelry, art, collectibles, silverware, and other high-value items may require additional coverage if you want protection for their full value.
Valuable items may have specific limits in a standard policy. A special endorsement or floater may provide additional protection when available.
Keep a detailed list of your belongings, including photographs, receipts, purchase information, and appraisals for valuable items when appropriate.
Create a Home Inventory
A detailed home inventory can help you estimate the value of your belongings and identify items that may need additional coverage. Keep photographs, receipts, and other documentation in a secure location so they are available if you need to make a claim.
Understanding Your Personal Property Coverage
Personal property coverage is an important part of homeowners insurance because it can protect the belongings that make up your everyday life. Before relying on your policy, review your coverage limits, deductible, valuation method, special limits, and exclusions.