A health insurance premium is the amount you pay to keep your health insurance coverage active. Understanding how premiums work can help you compare plans and estimate your overall healthcare costs.
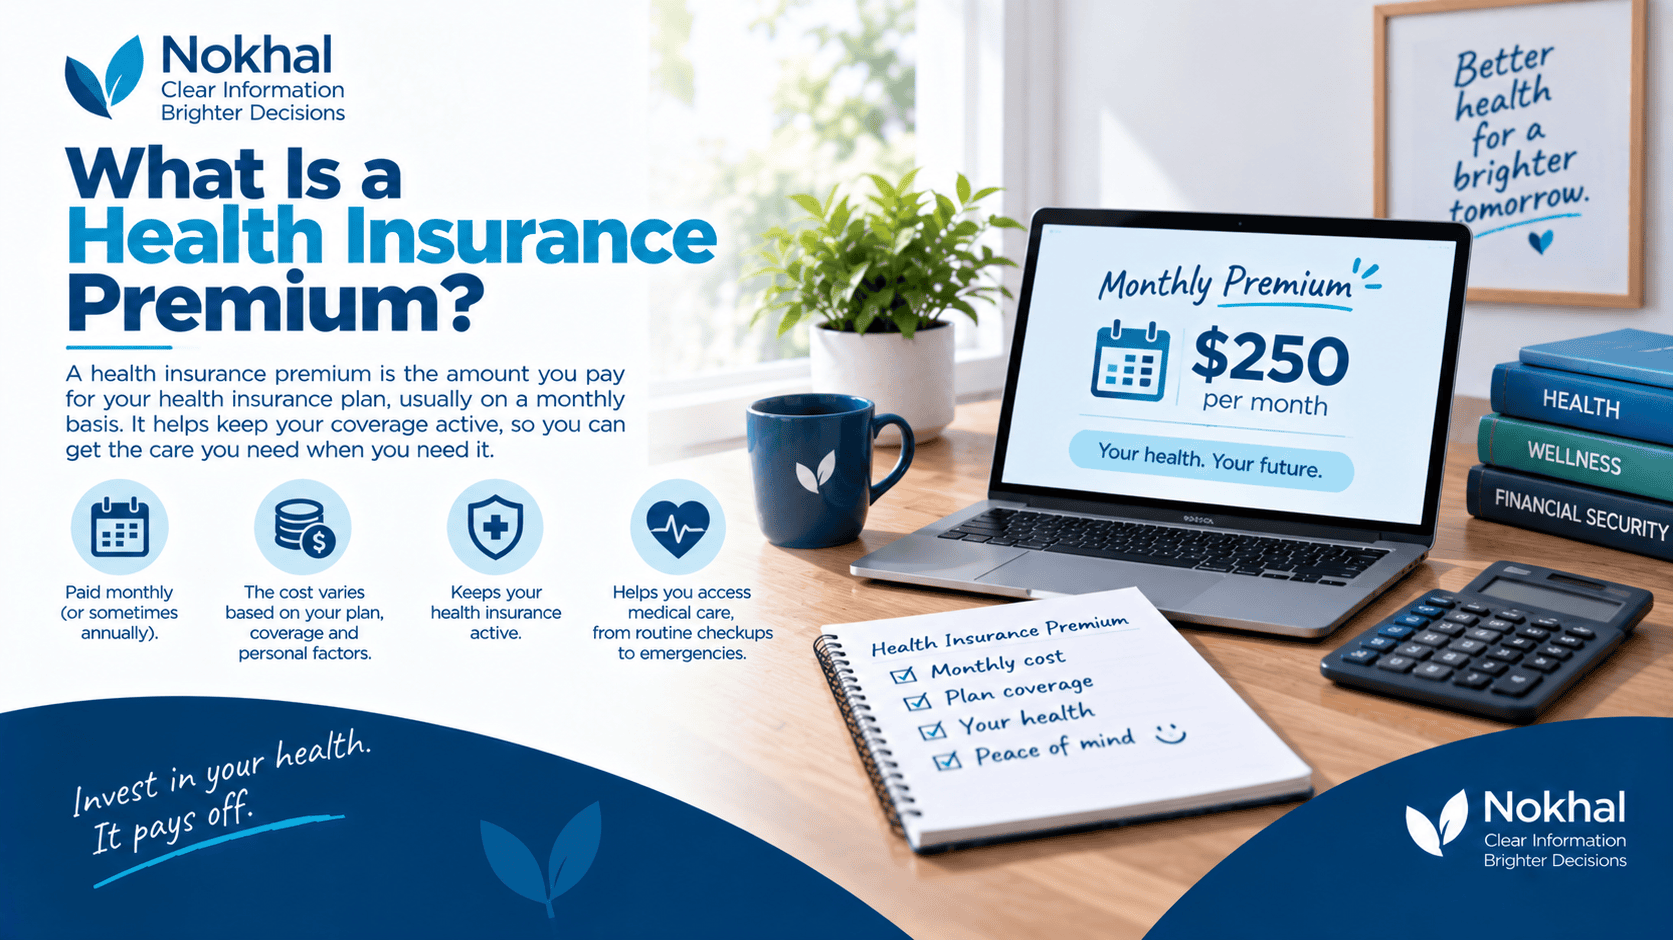
What Is a Health Insurance Premium?
A health insurance premium is the amount you pay for your health insurance coverage, usually on a monthly basis. You generally have to pay the premium whether or not you use medical services during that month.
For example, if your monthly premium is $300, you would generally pay $300 each month to maintain the coverage, regardless of whether you visit a doctor or use other covered healthcare services.
The premium is different from other healthcare costs such as deductibles, copayments, and coinsurance. Those costs generally occur when you receive covered care, while the premium is the recurring payment for the insurance coverage itself.
How Does a Health Insurance Premium Work?
When you enroll in a health insurance plan, the insurance company establishes a premium that you must pay according to the plan’s payment schedule. For many individual health plans, this is a monthly payment.
Paying the premium is important because coverage generally depends on keeping the policy active. For Marketplace plans, HealthCare.gov explains that coverage does not start until the first premium is paid, and ongoing premiums need to be paid on time to maintain coverage.
The premium itself does not necessarily mean that all medical services are free. You may still have a deductible, copayments, or coinsurance when you receive covered care, depending on the plan.
What Determines the Cost of a Premium?
The amount of a health insurance premium can vary from one plan to another. For Marketplace plans, federal rules allow insurers to consider factors including age, location, tobacco use, plan category, and whether the plan covers dependents.
| Factor | How It Can Affect Premiums |
|---|---|
| Age | Older adults can generally have higher premiums than younger adults under Marketplace rules. |
| Location | Premiums can vary depending on where you live. |
| Tobacco use | Marketplace insurers may charge tobacco users higher premiums, subject to applicable rules. |
| Plan category | Bronze, Silver, Gold, and Platinum plans generally have different premium and cost-sharing structures. |
| Dependents | Covering a spouse or dependents can increase the premium. |
For Marketplace plans, an important point is that an insurer cannot use your current health or medical history to set your premium.
A Lower Premium Does Not Always Mean Lower Total Costs
When comparing health insurance plans, looking only at the monthly premium can be misleading. A plan with a lower premium may have higher deductibles, copayments, coinsurance, or other out-of-pocket costs. Comparing estimated total yearly costs can give you a broader picture of what a plan may cost.
Premium vs. Deductible, Copay, and Coinsurance
It is easy to confuse a health insurance premium with the other costs associated with a health plan. Each one serves a different purpose.
Premium: The recurring amount you pay to maintain your health insurance coverage.
Deductible: The amount you generally pay for certain covered services before the plan begins paying its share, subject to the plan’s rules.
Copayment: A fixed amount you may pay for a covered healthcare service, such as a set amount for a doctor visit.
Coinsurance: A percentage of the cost of a covered service that you may pay after meeting your deductible, depending on the plan.
Together, these costs determine much of what you may spend on healthcare. HealthCare.gov recommends comparing estimated total yearly costs rather than focusing only on the monthly premium.
For some Marketplace plans, eligible consumers may also qualify for a premium tax credit that reduces the amount they pay toward their monthly premium. Eligibility depends on factors such as household information and estimated income.